If you have any questions, you are always welcome to contact us. We'll get back to you as soon as possible, withing 24 hours on weekdays.
Customer service
All questions about your order, return and delivery must be sent to our customer service team by e-mail at yourstore@yourdomain.com
Sale & Press
If you are interested in selling our products, need more information about our brand or wish to make a collaboration, please contact us at press@yourdomain.com
Help
If you have any questions, you are always welcome to contact us. We'll get back to you as soon as possible, withing 24 hours on weekdays.
Customer service
All questions about your order, return and delivery must be sent to our customer service team by e-mail at yourstore@yourdomain.com
Sale & Press
If you are interested in selling our products, need more information about our brand or wish to make a collaboration, please contact us at press@yourdomain.com
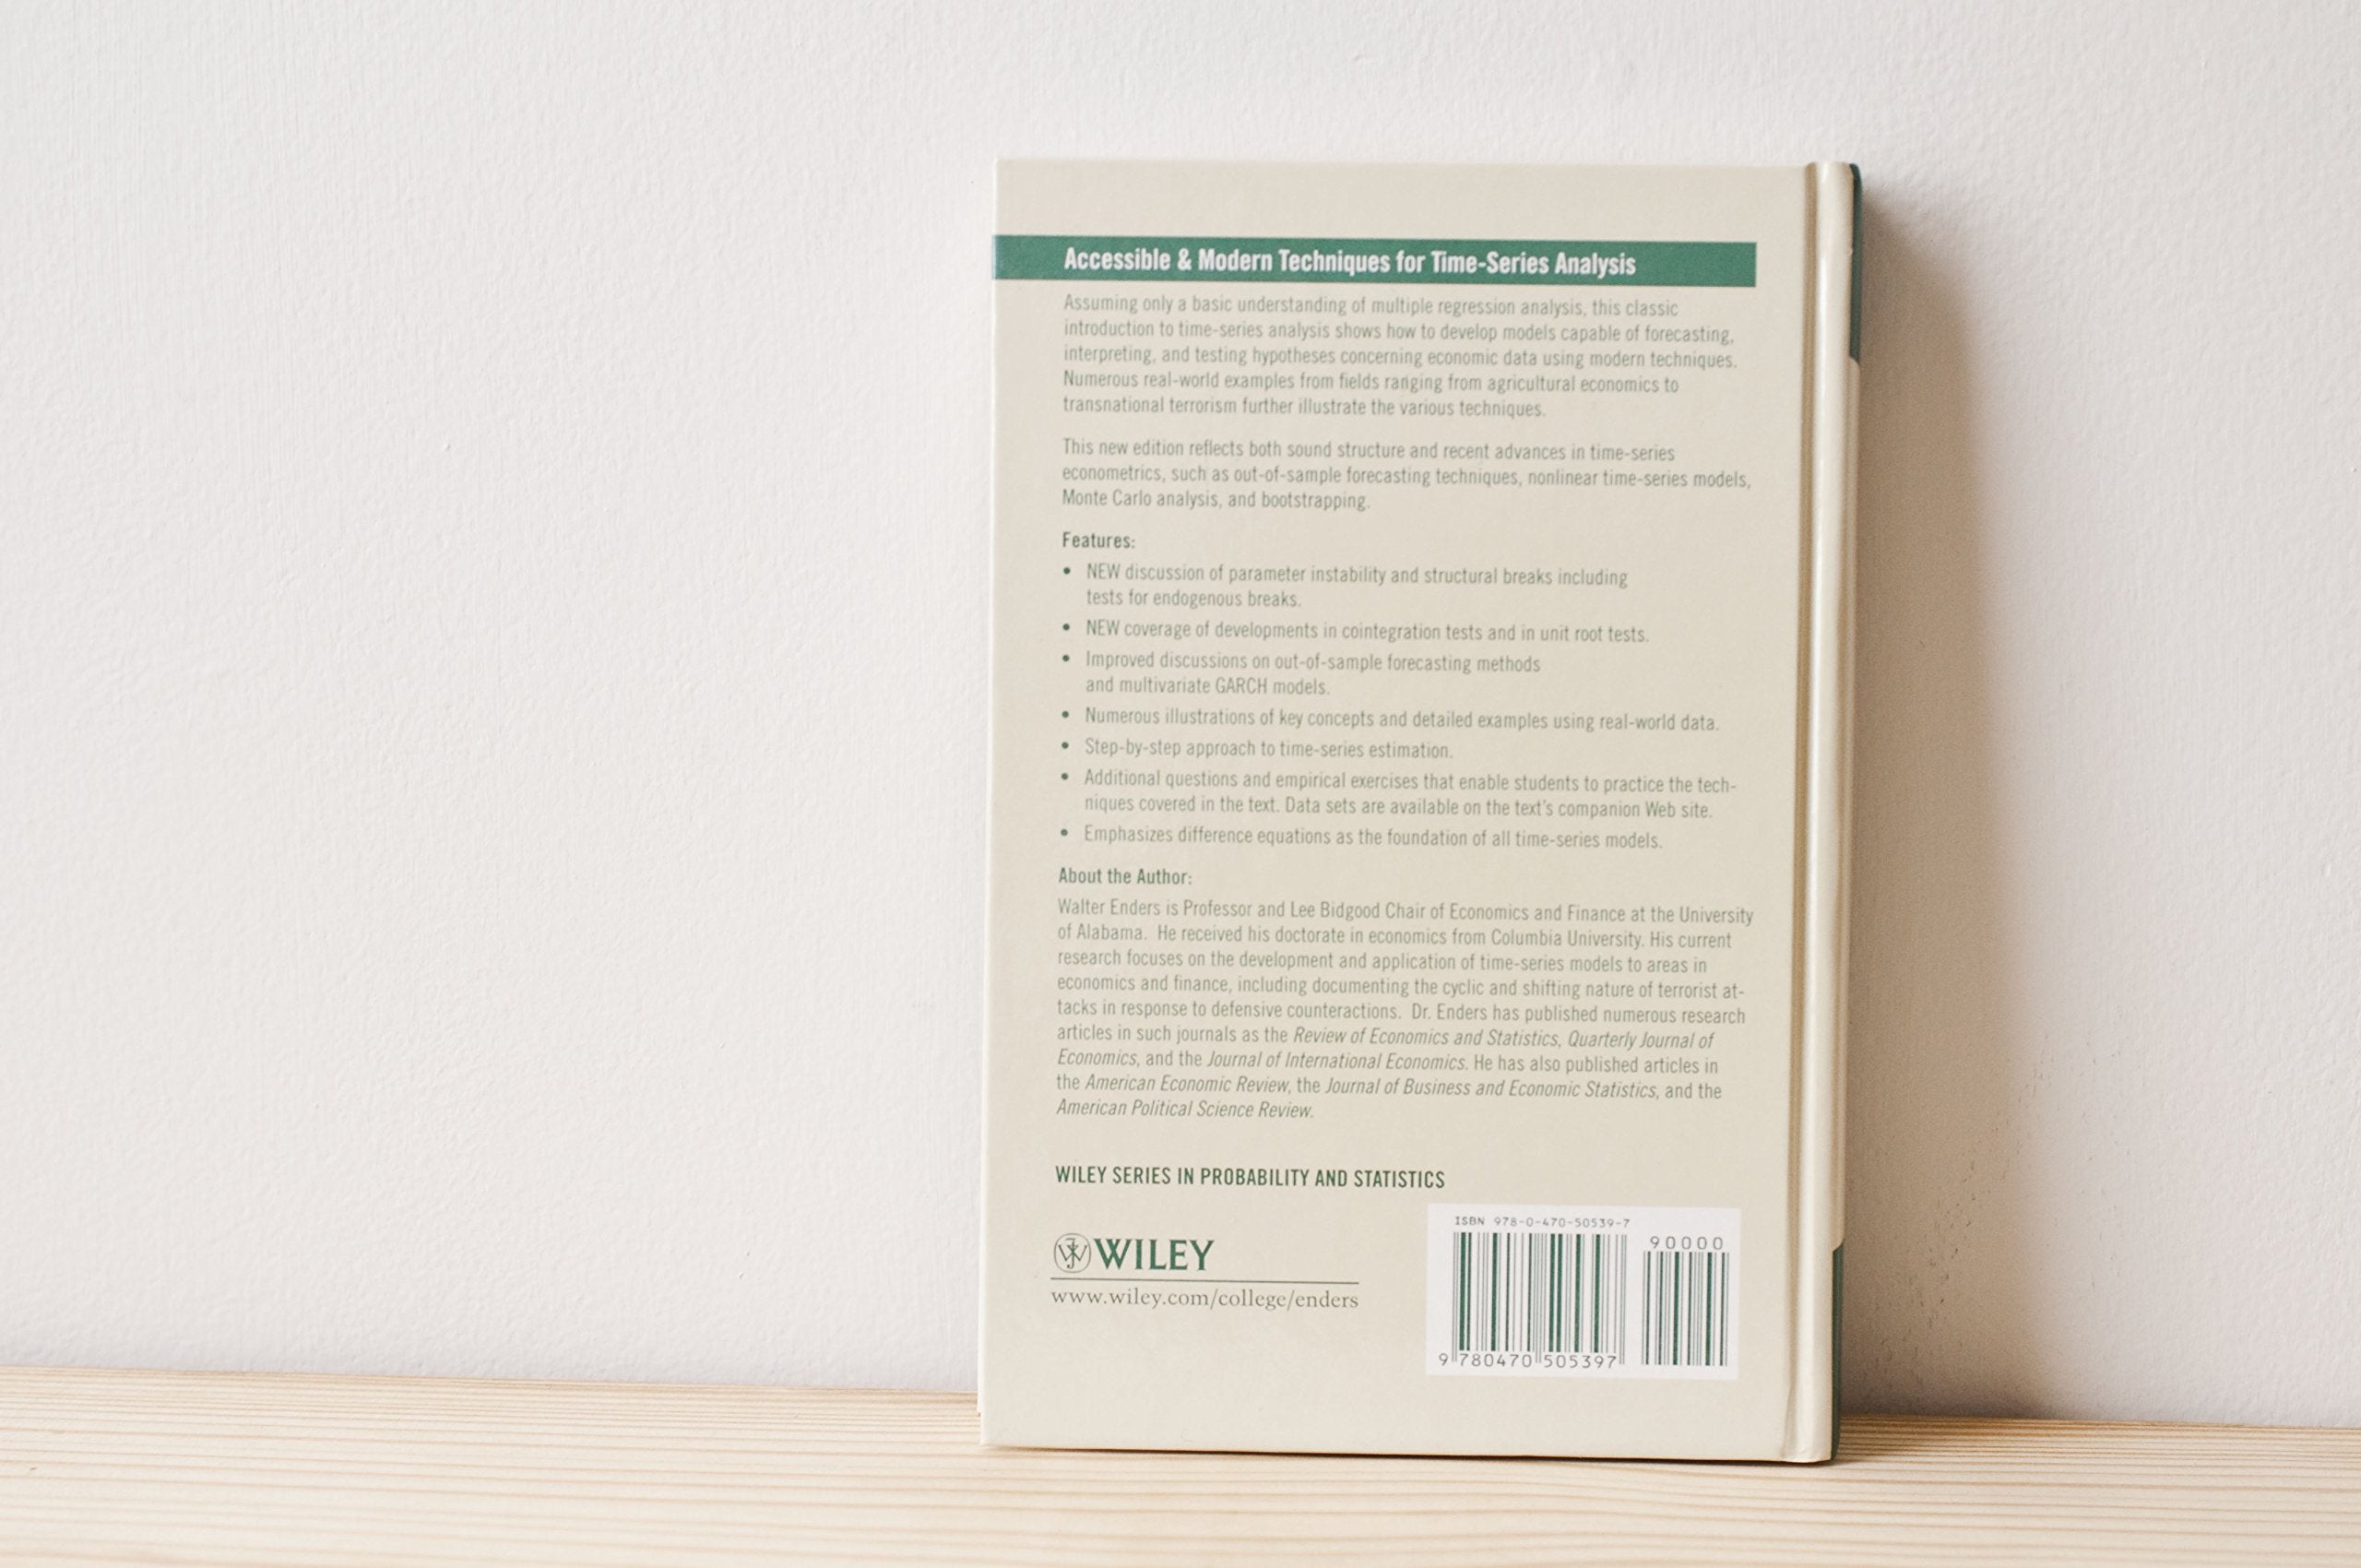
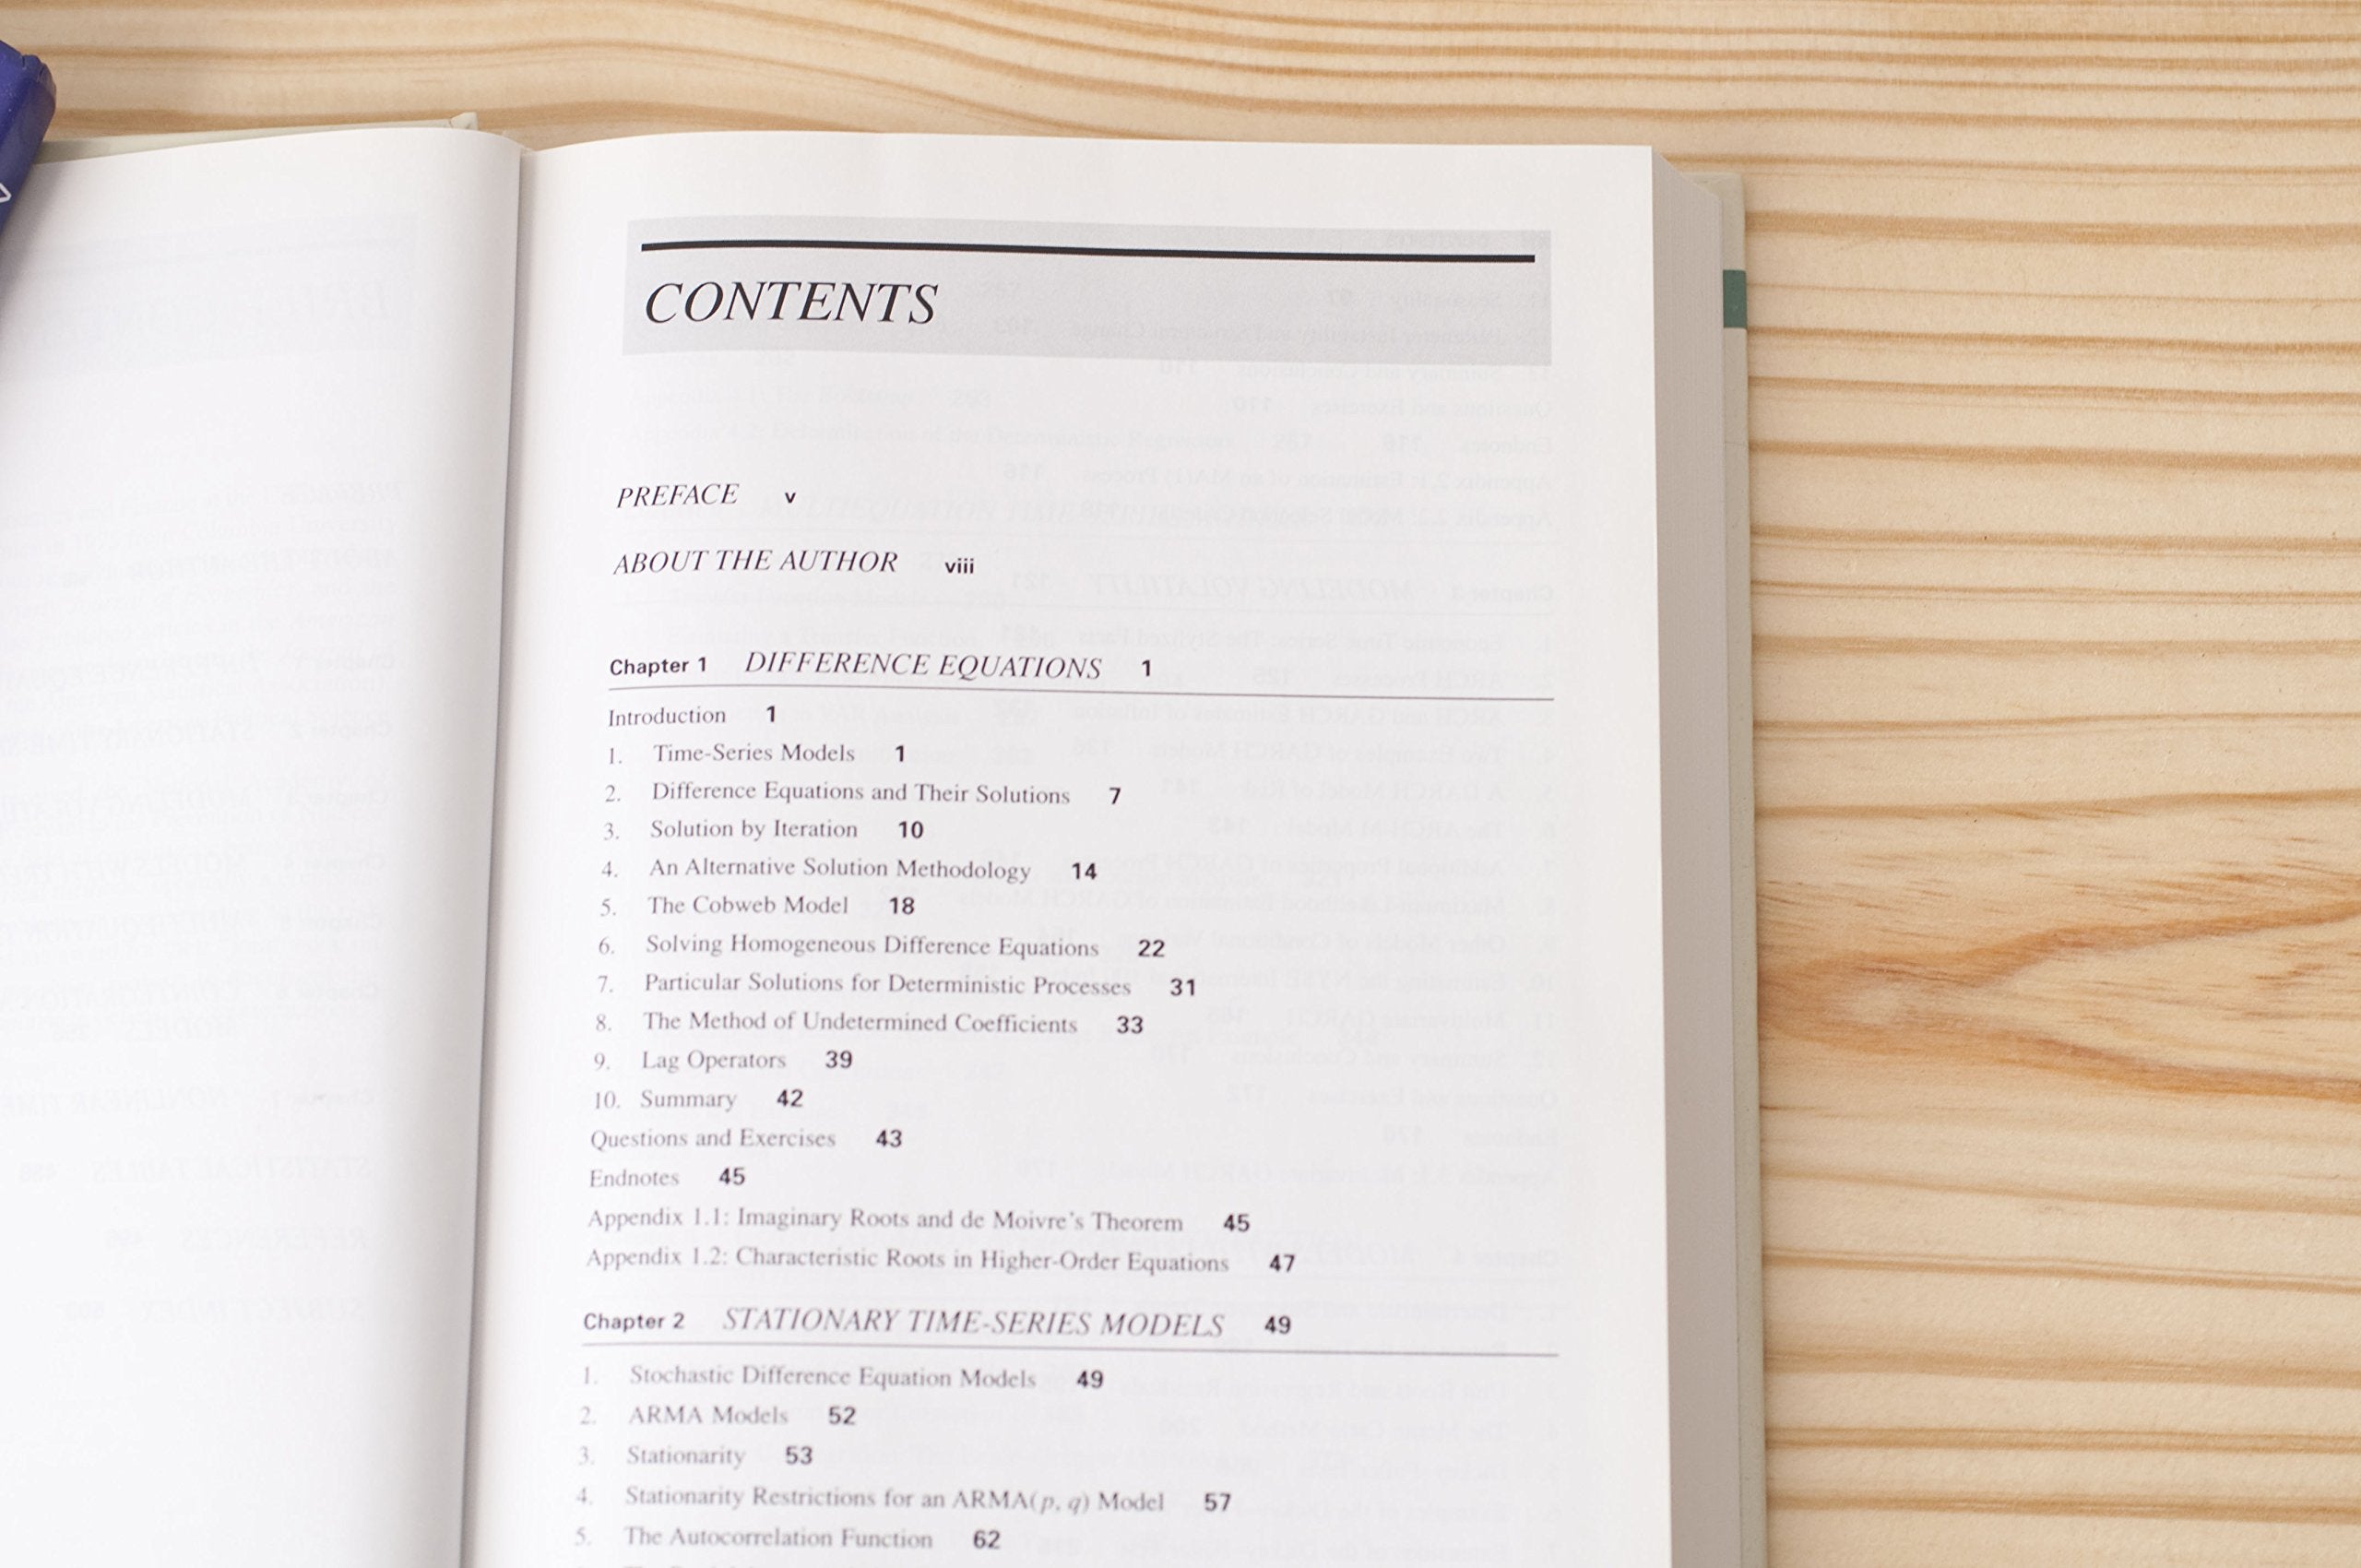
Enders continues to provide business professionals with an accessible introduction to timeseries analysis. He clearly shows them how to develop models capable of forecasting, interpreting, and testing hypotheses concerning economic data using the latest techniques. The third edition includes new discussions on parameter instability and structural breaks as well as outofsample forecasting methods. New developments in unit root test and cointegration tests are covered. Multivariate GARCH models are also presented. In addition, several statistical examples have been updated with realworld data to help business professionals understand the relevance of the material.
⚠️ WARNING (California Proposition 65):
This product may contain chemicals known to the State of California to cause cancer,
birth defects, or other reproductive harm.
Q: What is the main focus of 'Applied Econometric Times Series'?A: The book provides an accessible introduction to time-series analysis, emphasizing model development for forecasting and hypothesis testing in economic data.
Q: Who is the author of this book?A: The author of 'Applied Econometric Times Series' is Walter Enders.
Q: What is the publication date of this edition?A: This edition was published on January 1, 2009.
Q: How many pages does the book have?A: The book contains 517 pages.
Q: What are some key features of the third edition?A: The third edition includes discussions on parameter instability, structural breaks, out-of-sample forecasting methods, and updated statistical examples with real-world data.
Q: What is the condition of the book?A: The book is classified as 'Used Book in Good Condition'.
Q: Is the book hardcover or paperback?A: The book is a hardcover edition.
Q: What topics in econometrics are covered in this book?A: The book covers unit root tests, cointegration tests, and multivariate GARCH models.
Q: Who would benefit from reading this book?A: This book is designed for business professionals and students looking to understand time-series analysis and its applications in economics.
Q: Is this book suitable for beginners in econometrics?A: Yes, it is written to provide an accessible introduction, making it suitable for beginners in econometrics.
For MAP (Minimum Advertised Price) violations and Intellectual Property (IP) or Trademark concerns, please contact:
support@ergodebooks.com
⚠️ California Proposition 65 Warning: Some products sold on this website may expose you to chemicals known to the State of California to cause cancer, birth defects, or other reproductive harm. For more information, visit www.P65Warnings.ca.gov.